Loan settlement sure does feel good, until a borrower realizes they have another issue months or years later. Three months later. Six months later. When applying for that home loan, or personal loan, credit card or even new business finance, they pull out their credit report and find the word “Settled” printed neatly against an old loan account.
It seems harmless enough, but it opens up a lot of questions. Didn’t we already settle that loan? Why doesn’t that account say “closed”? Is the next bank going to reject me as well? Can’t you fix this? Did I just spend money for nothing? !
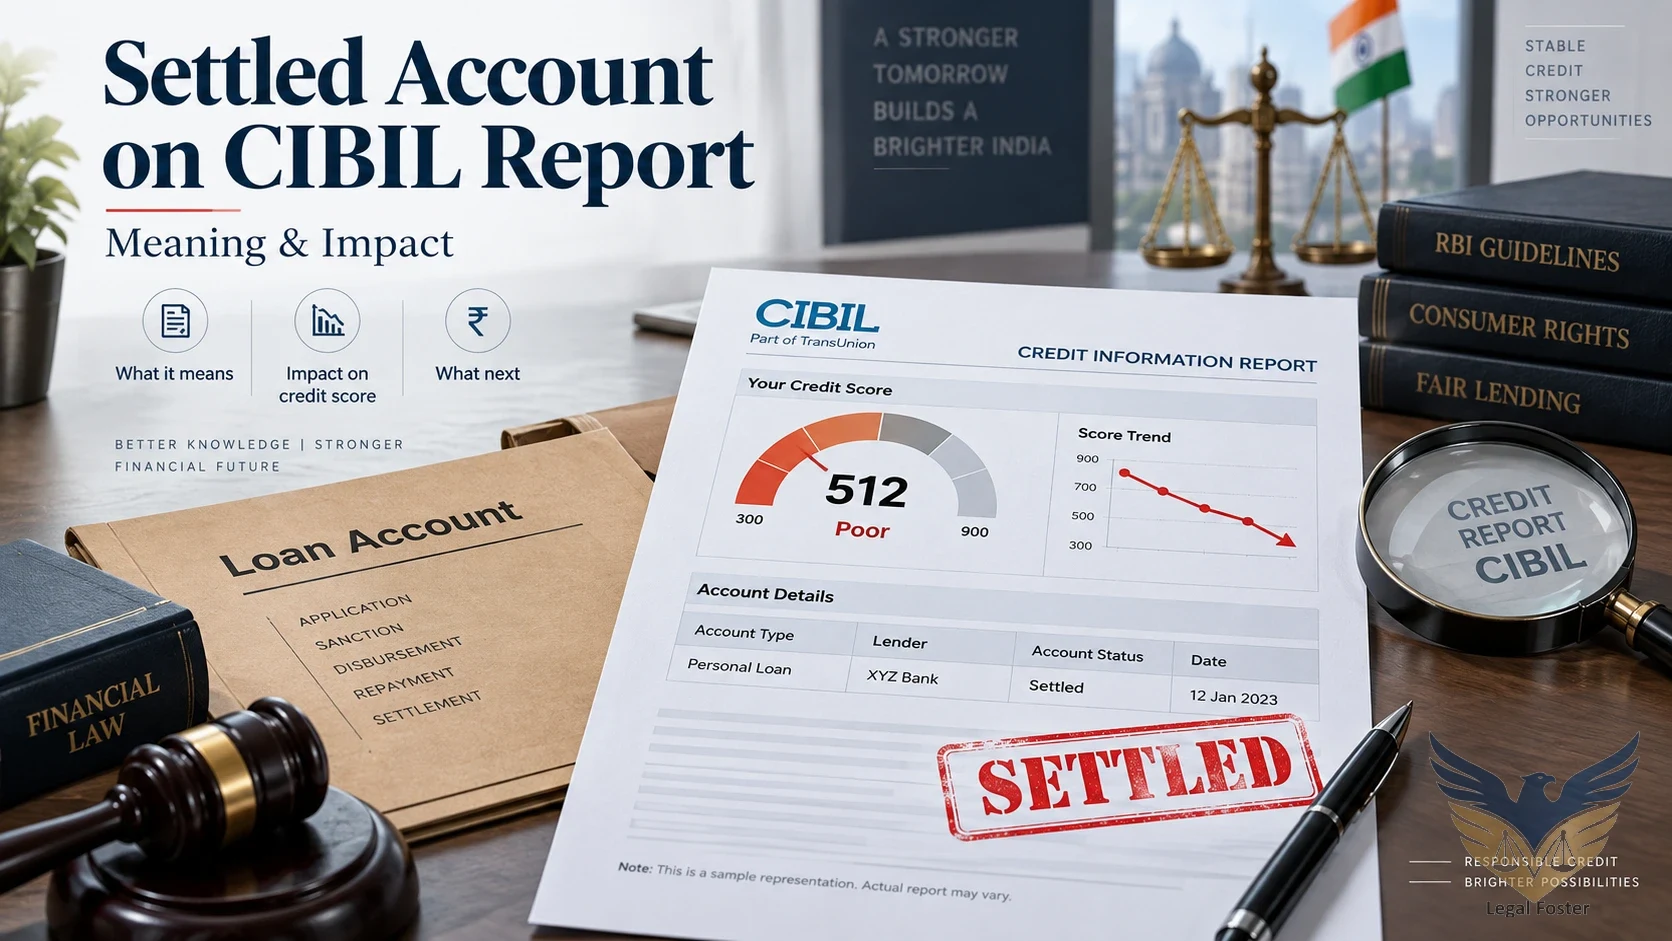
For the majority of borrowers, having a settled account show up on your CIBIL report means that your lender took less than what your loan contract stipulated, and then informed the credit bureaus that this account was settled according to terms agreed to by you and the lender. Read TransUnion CIBIL’s own description on their website: they explicitly state that a “settled” account is not the same as an account that is “closed”. For most borrowers, a “closed” account would mean that an account was paid off in full.
Why should borrowers care about what category an account falls into? Well, the recovery lenders have stopped calling you months ago, but banks care about your past loan repayment performance when you apply for new credit. Having settled a loan in the past affects your application when you apply for that home loan, or car loan, or business loan, or next credit card.
Ultimately, having “settled” on your credit report isn’t the real issue. What matters is if the credit-reporting was done correctly, if the lender has updated the account to show what is currently owed (if anything), and do you the borrower have any paperwork that backs up your claim.
As borrowers, if you find yourself in this situation, Loan Settlement Agency can go over any settlement paperwork you have, communications with the lender, and what is being stated on your credit report. If we need to, we can even confer with Advocate BK Singh to help you understand the difference between a valid settlement and incorrect credit reporting.
Why Does a Settled CIBIL Account Matter for Borrowers in India in 2026?
As per RBI’s latest circular mandated last year, covered lenders and credit bureaus will now report credit data fortnightly beginning January 1, 2025, as long as they meet prescribed reporting and ingestion deadlines. Expect credit reports to have timelier information about you, the borrower.Once every two weeks, credit information on account statuses, balances and payments will be updated. This means an old settlement, incorrect outstanding balance or update that was never submitted will appear on future credit checks a lot sooner than you may think.
If you reside in Delhi NCR, Noida, Ghaziabad, Gurugram, Greater Noida, Faridabad, Mumbai, Bengaluru, Hyderabad, Chennai, Jaipur, Lucknow or any other city in India, here’s the bottom line. When a lender pulls your credit to review your new credit application, they’ll be looking at your previous repayment history to determine if you qualify for that new credit opportunity.
That borrower who thinks they can buy a house two years after settling up that personal loan won’t realize that old ₹0 balance is still hurting their credit score. For this very reason, Loan Settlement Agency urges borrowers not to throw away your settlement letter, payment receipts, no-dues letters and your latest credit report. Just because you paid, doesn’t mean the reporting was completed accurately.
Quick Facts
- “Settled” and “closed” aren’t usually interchangeable on a credit report.
- Settled typically means that less than what was contractually owed was received.
- Credit reports issued by CIBIL will show credit account statuses as open, closed, settled, written-off, etc.
- Covered entities must now update credit information on a biweekly reporting cycle as per RBI guidelines.
- Credit information can be contested by the borrower if deemed inaccurate.
What Does “Settled” Actually Mean in a CIBIL Report?
What a settled loan essentially means is that the borrower hasn’t paid back the entire amount owed but the lender settled for a lesser amount than what was owed in order to commercially close out the account.
According to CIBIL’s own FAQ’s for consumers, “If the amount paid up under settlement is less than what is due, then lender can show the account as settled. If the borrower pays up the entire amount due, this status is usually reported as closed.”
That’s why it’s critical for borrowers to understand all the immediate and future consequences of agreeing to a loan settlement. There’s the short-term benefit of lessening your debt. However, what you sacrifice is the possibility of having a “settled loan” show up on your credit report.
If you’re unsure what a settled loan would mean for your credit report, Loan Settlement Agency can go over your credit report with you and your loan settlement paperwork.
Who Should Review a Settled Account Before Applying for Fresh Credit?
Any individual planning to apply for a significant loan should get and review an aged account, in good standing, as soon as possible.
This includes salaried individuals wanting to apply for a home loan, business owners applying for working-capital loans, professionals applying for personal loans, families looking to finance education or even borrowers who wish to re-establish their credit worthiness after a financial misstep.
Submitting loan applications only to be denied time and time again without first understanding your current report can be disheartening.
As the borrower, you should want to know:
How much was the ORIGINAL loan amount? How much did you ultimately settle for? What exactly did you sign in the settlement letter? Did the lender provide you with an NOC? Does your report still show that amount as owed? Was a follow up payment made to the creditor? Loan Settlement Agency can assist borrowers in reviewing this information prior to re-applying to lenders.
How Should a Borrower Deal With a Settled Account?
That depends on if the entry itself is accurate or not. If you paid less than what you owed the lender when you settled the loan, simply asking them to delete "settled" from your report may not be entirely fair. Check with the lender, to see if there is an amount due to satisfy the account and they will mark the reporting status as agreed upon once they are satisfied. (As much as is financially possible for you.)
CIBIL has given an example where the borrower cleared the due amount, obtained an NOC from the bank and raised a dispute and the status was changed after the lender verified.
Please don't assume that because the above example worked that ALL settlements can be changed. Every lender has there own copy of your record, payment history and facts surrounding the settlement.
If the report is inaccurate, keep records and dispute, don't assume. Consulting with Loan Settlement Agency can help you figure out if this is a true settlement issue or incorrect reporting to be corrected.
Which Documents Should You Keep After Loan Settlement?
Poor documentation will cause you grief later.
A borrower would ideally want to retain:
- sanction letter(s) for the loan; settlement/OTS offer;
- written acceptance from bank; receipts/bank statements;
- email chains; WhatsApp trails/SMS trails wherever possible;
- ND certificate/NOC if issued; account statement showing adjustment entries;
Past CIBIL and updated CIBIL report; complaint/dispute reference numbers.etc
Agreements made on email/SMS/WhatsApp are better than verbal assurances.
“If the recovery agent quotes you that “Your CIBIL will be squeaky clean after you pay up”, politely ask him to forward you the settlement clause from the agreed email before you trust his words.”
BK Singh can assist you in analysing these documents should the bank report something different later than what was agreed to put in writing.
How Long Can CIBIL Correction or Updating Take?
But when you repay your loan, you expect your credit report to reflect that change immediately. For example, under RBI’s current reporting guidelines, covered entities are required to report information on a bi-weekly basis and are given specific deadlines by which to transmit and upload reported information.
It may take longer to correct if there is a dispute. First, the reported information will have to be verified with the respective credit bureau. Second, RBI’s framework for consumer protection allows for a 30-calendar-day resolution period for eligible updates or correction requests, after which eligible compensation may become available should all of the above requirements be met.
That being said, borrowers shouldn’t file multiple disputes if they aren’t keeping track of ref numbers and other paperwork. If it’s been weeks and you still don’t have a resolution, let Loan Settlement Agency help you compile your account history and decide how to proceed.
When Should You Consult a Loan Settlement Lawyer?
Legal help might be necessary if your case is more complex than a basic CIBIL dispute:
Consult Lawyer BK Singh if:
- your lender is continuing to report contrary to your settlement letter’s terms;
- you’ve paid what was requested but your statements aren’t tallying up;
- the bank or finance company says you owe them money even though you’ve accepted a settlement letter;
- you’ve received an NOC from your lender but they’re continuing to report derogatory information about your account;
- you’ve tried sending letters but haven’t seen any success;
- you have multiple accounts linked to your loan;
- you’re currently in the process of working out a settlement and are concerned about the impact it will have on your future credit;
or if you’re experiencing recovery harassment in addition to credit-report issues.
However keep in mind that a lawyer can’t make negative history suddenly go away if the settled status is rightfully placed.
How Can Loan Settlement Agency and Advocate BK Singh Help?
Loan Settlement Agency guides borrowers under pressure from debt, loan settlement documents and post settlement credit-report queries all across India.
Analysing the situation is better than making hollow promises.
The settlement letter, proof of payment, communication with the lender and latest CIBIL report can be analysed. Once we analyse these aspects it will be clear if its a legitimate settlement fallout, wrong entry or an outstanding amount or due post settlement work. BK Singh can review the facts and correspondence if there is a need for a legal opinion.
Borrowers who want to avoid payment and are looking to settle can also receive documentation advice. Because knowing the impact on your credit score should take place before you accept the settlement, not after.
Frequently Asked Questions
1. What does “settled” mean in my CIBIL report?
If your loan account shows up as settled on your credit report it means that your lender agreed to accept a lesser amount than what your total dues were when you cleared your dues. Settled indicates that the full amount was not paid.
2. Will a settled account hurt my credit score?
Yes. A settled account will negatively affect your credit score and future lenders may not view it favourably.
3. What is the difference between settled and closed account?
Loan accounts marked as closed means that you repaid your entire loan amount according to the terms agreed upon between you and the lender. Settlements are generally used when only a portion of the dues were paid as per an agreement/settlement between you and your lender.
4. Does settled eventually become closed?
Yes. After you clear your dues as per your lender’s agreement and they agree to remove or change the status from settled to closed on your loan account, it will be updated as such.
5. Why does settled still show on my CIBIL score even after paying?
If you paid your loan dues as agreed upon in your loan contract with your lender, they can report your loan account as settled on your credit report. There can be delays in your loan repayment status being updated or your lender might have incorrectly reported your loan account status. Contact your lender to ask them to update your loan account status.
6. Can I dispute settled on my credit report?
Yes. Since you have the right to dispute inaccurate information on your CIBIL report, you can raise a dispute for incorrect information on your credit report. Provide them with proof of payments made towards your loan like receipts, the settlement letter, your no dues certificate or NOC from your lender.
7. Can I be denied loan from bank due to settled loan?
Well not really. Just because your loan is settled will be considered when applying for loans but you may still get your loan approved as different lenders have different loan lending policies.
8. What paperwork should I keep after loan settlement?
Keep documents such as your loan settlement letter from your lender, bank statements with loan payments, any email conversations with your lender regarding your loan, your NOC from your lender, loan account statement and your updated CIBIL score.
References.
9. Do I need a lawyer to deal with CIBIL settlement?
If your lender has reported your loan payment inaccurately and you have proof that what they are reporting is different from what you had agreed to in writing, you can get a lawyer. Another instance where you may need to contact a lawyer is if you’ve made several attempts to get your lender to update your loan information with CIBIL but they refuse to do so.
10. How can Advocate BK Singh help me?
Advocate BK Singh can assist you by going over your loan settlement documents, proofs of payment, and any email correspondence with your lender. Contact Advocate BK Singh for more information.
Final Thoughts
Loan Settlement! Don't Ignore Just Because Calls Have Stopped An account that has been settled as paid in full, as shown on a CIBIL report should never be ignored. Just because the phone calls have stopped, does not mean that you can blank it out of your mind. For the most part this entry tells the potential lender that your previous account was settled for less than what you originally contracted to owe.
Depending on what actually happened with that account, the lenders record and any payments that were made after the settlement amount was paid, that entry may be able to be changed at a later date. Review your latest report. Keep every settlement letter. Dispute inaccurate balances. Don't continue to apply for credit until you know what your report says you owe. If your account status is showing incorrectly or you are currently working towards another settlement you may want to contact Loan Settlement Agency and BK Singh for document driven help.