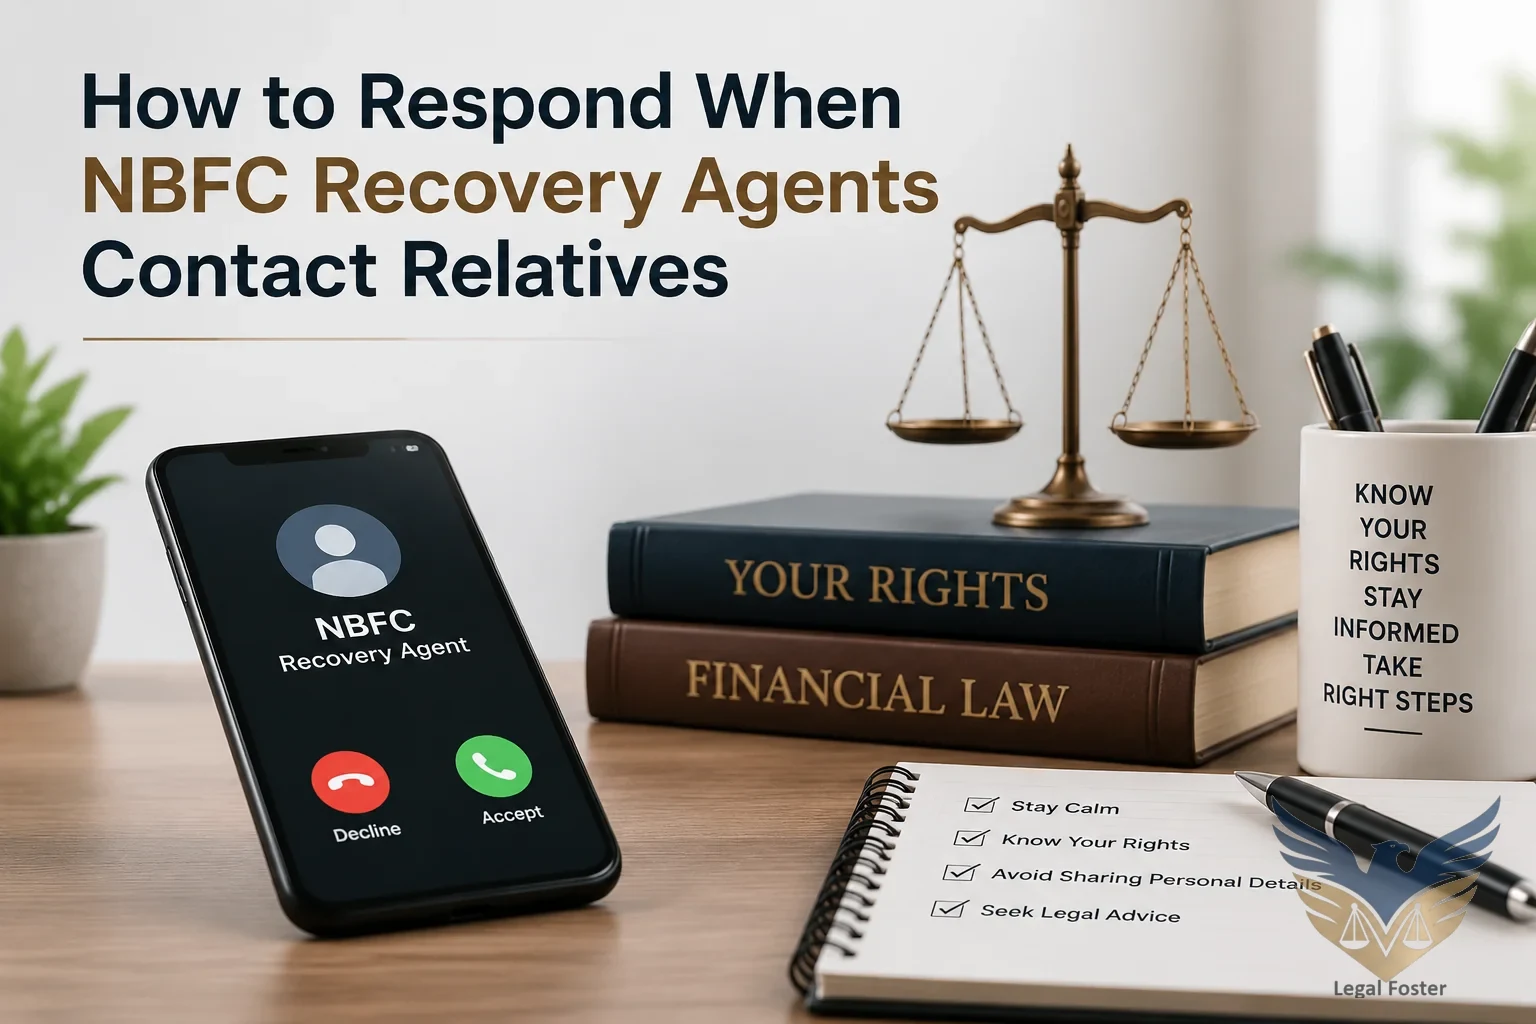
How Borrowers Can Respond When NBFC Recovery Agents Contact Their Relatives
If your Equated Monthly Installment (EMI) goes unpaid, what began as your personal loan problem quickly spirals into a problem for your family once the NBFC agent starts calling your wife, parents, siblings, friends or employers. You may be anxious about your financial situation. But having your family harassed causes further shame, anxiety and wholly avoidable family tension.
NBFC agents can contact your family members if they are co-applicants or guarantors or have some connection to your loan. However, an agent cannot harass, shame or bully your family members whenever they choose. In fact, the RBI instructions say agents cannot harass or intimidate borrowers and mentions the privacy of borrowers' relatives, referees and friends.
If you're receiving NBFC collection calls about a loan in Delhi NCR, Noida, Ghaziabad, Gurugram or any other city in India, take a deep breath. Start by documenting the calls, identifying who is calling you, confirming details about the loan account and speaking to the NBFC through its grievance redressal mechanism.
Loan Settlement Lawyers can assist you in determining whether the calls are just part of normal collections, whether it's a complaint that can be escalated or whether you should consult with a lawyer about your legal options. We can help you evaluate your options if you wish to restructure your loan or do OTS or loan settlement.
Why Does Contacting Relatives by Recovery Agents Matter in 2026?
Approaching a relative will not lead to wrongful recovery per se. Facts matter. A co-borrowing/guarantor spouse is not at the same place as say the elderly parent of a borrower who is unrelated to the loan contract.
RBI said in its 20 22 directions that regulated entities would be liable for the acts of their recovery agents. It prohibits “intimidation” or “harassment” including “conduct which is aimed at the public humiliation of the debtor or otherwise abuses or insults him or attempts to intrude upon the debtor’ s privacy or that of his family members, referees and friends”. Calls that are threatening or anonymous are also forbidden. Recoveries calls cannot occur before 8:00 am or after 7:00 pm.
With regard to digital lending, RBI has underlined the importance of data privacy and fair recovery practices separately. REs would continue to be liable for actions of their lending service providers. Information on recovery agents would need to be disclosed even in digital lending.
That line assumes significance in Delhi, New Delhi, Noida, Greater Noida, Ghaziabad, Gurugram, Faridabad and elsewhere in the country. Just because someone has taken a loan and is under financial stress, he cannot be publicly humiliated or abused during the loan recovery process.
- NBFC is liable for actions of its agents including recovery agents.
- Intimidation or harassment while collecting dues is barred by RBI instructions.
- Harassing a borrower’s referees and friends and family members’ privacy are also covered under RBI recovery-agent instructions.
- Curbing collection calls before 8: 00 a.m. and after 7:00 p.m. day is distinctly mentioned under RBI Directions for Recovery Agents 20 22.
- Example: Unlike a co-borrower or guarantor, an entirely family member who is unconnected may not have any contractual obligation.
- Keep a log of calls, texts, emails etc. as evidence of wrongdoing before complaining to the lender.
What Does It Mean If an NBFC Calls Your Relatives?
Best read aloud. Consider RBI's bullet points about recovery calls to relatives. Evaluate the borrower's connection to the loan and the substance & intent of the call.
Take for instance the borrower defaulted on a personal loan and the lenders collection agent called the father. If the father is not the borrower/guarantor, the legal & regulatory ramifications are not the same as if the father had signed paperwork guaranteeing the loan.
The intent of the call factors into the agents behavior as well. A professional request for the borrower to call the lender is different than the agent telling a family member the borrower is a fraudster; threatening the family member; calling their job multiple times; or using vulgar language.
What Legal Framework Applies to NBFC Recovery Agents?
Rules governing obligations of regulated entities that outsource operations to recovery agents have also been stipulated by RBI.
For example, even though the RBI (Directions on Recovery Agents) dated 12 August, 20 22 state that ‘the responsibility and accountability for the outsourced function(s) rests with the regulated entity’, it clarifies “without resorting to intimidation/ harassment, intimidation of the borrower or his family members or his referees/friends.”
This of course all sits atop RBI’s broader regulation on NBFCs, the contract between lender and borrower, and any other applicable legislation.
As far as digital lending agreements are concerned specifically, RBI’s Digital Lending Guidelines mention privacy, data collection, lending service providers, and even recovery.
Digital lending complaints are covered under RBI mandating regulated entities to have a grievance-redress mechanism for handling such complaints.
If you happen to be a borrower and find yourself facing an issue with your lender, don’t assume it’s a criminal issue. NBFCs may have the contractual right to recover the amounts due, but they can’t just do anything to recover that money.
What Should You Do If Recovery Agents Keep Calling Your Family?
Screenshots of any WhatsApp messages, SMS messages and emails. Write down numbers from where calls are being received. Maintain a record of date, approximate time of call, name mentioned by the caller, name of the agency, if any and what was said during the call.
If the family member is the one who has received the call, get them to write down what happened during the call immediately, while it is still fresh in their mind. Do not incite them to question the recovery agent or behave confrontationally with the caller.
Once you have recorded the above details, contact the NBFC directly through its official customer-care or grievance-redressal number. Provide them with NBFC loan account details and clearly state that the person from whom recovery is being attempted does not owe money to the NBFC, if that is the case.
Ask the NBFC to give you the authorised recovery agency’s details/name of the officer in charge of the loan account wherever applicable.
A Loan Settlement Lawyer can assist a borrower by analysing the documents and drafting a written complaint to move forward with the matter, if necessary.
Can a Borrower Complain About Recovery-Agent Harassment?
Yes. If the borrower is dissatisfied with the resolution of the complaint he can escalate the matter to the concerned regulated entity if the mode of recovery is inconsistent with RBI directions or lender’ fair- practices code. Complaint – Do not use hyperbole, simply narrate facts. Include details like who called you, what were you told on phone, how many times you were called, were you acquainted with the person calling you ( about loan etc.).
RBI’ Integrated Ombudsman scheme provides borrowers with a mechanism for resolution of eligible complaints against service deficiency by regulated entities, through an alternative dispute redressal channel. The Reserve Bank–Integrated Ombudsman Scheme, 2021 came into force with effect from July 1, 2021, and replaced the Ombudsman Scheme, 2017 with respect to complaints pertaining to issues covered under the said scheme.
First and foremost is still applicable as a practical first step. Approach the concerned regulated entity through its own grievance redressal channel and get an acknowledgement of your complaint. Only after this, depending on the relevant scheme and facts of your complaint, can the complaint be escalated to RBI’ grievance redressal mechanism if it is an eligible complaint. Your loan settlement lawyer will help you with the paperwork and the escalation channel.
What If the Relative Is a Co-Borrower or Guarantor?
That is not true if the relative was a signatory on the loan documents.
A co-applicant can be contractually liable for the loan. A guarantor can be legally liable for the guarantee. Simply referring to someone as a “relative” does not create liability.
For this reason, borrowers should ignore generic information telling them the NBFC “will never” contact relatives.
The facts matter. The person’s contractual obligation on the debt matters. The method of recovery the lender is using matters.
If your parent, spouse, sibling or business partner signed as a guarantor, ask them for a copy of the loan and guarantee agreements before accusing the NBFC of improperly contacting them.
Loan Settlement Lawyer can review those documents and explain to you the difference between contractual liability and collection activity that may be a separate violation.
What If the NBFC Is Calling Relatives Because the Borrower Has Defaulted?
Defaults don’t justify every recovery method
Keep in mind that an NBFC can only attempt to recover that money which is owed to them legally. If the conditions of the loan, contract and account allow it, the lender can ask for payment, restructure the repayments, square up, prosecute, or foreclose on collateral (wherever legally possible).
However RBI also includes guidelines for how the recovery agents should act.
So the customer shouldn’t take advantage of either behavior.
Don’t assume every phone call to collect on the loan is harassment because you’re stressed. Don’t assume an agent can publicly shame you or threaten you because you owe them money.
What Documents Should You Take to a Lawyer?
A lawyer will typically need to see the underlying documents to give any meaningful advice.
Keep your loan agreement/sanction letter, latest account statement, repayment history and all correspondence with the NBFC. This includes any legal notice or settlement offer received from the NBFC/recovery agent and correspondence with recovery agents ( emails, sms etc). Also keep copies of screen shots of the above.
If the loan is against your business loan, keep relevant business records that explain why you've been unable to repay. To the extent you are considering a settlement, the borrower’s actual ability to make a proposed payment is also commercially important.
Loan Settlement Lawyers can review what you've compiled and give you a useful opinion on whether the issues sooner relate to recovery tactics, settlement, restructuring, litigation or some combination thereof.
When Should You Consult a Lawyer?
Legal consultation can be helpful especially if the case has gone beyond statements and payment reminders.
You may consider consulting a lawyer if debt collectors call third parties like your family members many times about the loan, threaten you with violence or job loss, disclose unnecessary information about your debt to third parties, send you vulgar messages or continue after you’ve sent a written notice to complain.
Speak to a lawyer at the earliest if you’ve received a legal notice, notice against a secured asset, summons from court or tribunal or a settlement letter with a short response time to pay the debt. Remote legal advice also makes sense for borrowers from Delhi NCR (Delhi, Noida, Ghaziabad, Greater Noida, Gurugram) where most of the dispute is on papers i.e. notices and communications.
How Can Loan Settlement Lawyers Help?
Loan Settlement Lawyer: Loan settlement, recovery & other bank related queries by borrowers.
Notice: Initial consultation would include account review. Loan agreements, payments made, outstanding balance, recovery notices/calls and legal notice(if any) would be reviewed. Provided that if relatives are being threatened/harassed then effort would be to record such activity and identify suitable grievance/legal remedy. However if the borrower has a genuine case of repayment hardship then it might also be essential to review the borrower's overall financial position (to analyze settlement or an alternative repayment strategy.)
Loan documents, account review, recovery calls/messages and clarification on the status of a loan can be managed by Advocate BK Singh. It's better to give a legal insight once the documents are reviewed rather than assure that every grievance would lead to XYZ results.
If you want to know about borrower issues in general, you can refer to Borrower Protection & Rights.
Frequently Asked Questions
1. Can an NBFC recovery agent contact my relatives?
An NBFC can call your relative under certain circumstances. Harassment & intimidation is never acceptable but calling family members could be considered intrusive. If your relative co-signed or guaranteed the loan it may impact their rights as well.
2. Can recovery agents call my parents regarding my loan?
If your parents are not a liable party for the loan (co-applicant/guarantor) they have different rights than those who applied for/guaranteed the loan. Document/recording is recommended if confidential information is revealed or you receive continuous calls.
3. What should I do if recovery agents threaten my family members?
Document all calls/messages/voicemails etc. Recording the harassment they conduct is beneficial. Consider sending the NBFC a formal complaint in writing if family members have been abused, harassed, or threatened. Talk to a lawyer about possible legal action.
4. Can loan recovery agents tell my relatives about my loan?
Loan providers must follow RBI guidelines with respect to a borrowers privacy. It is not appropriate to share details about your loan but may not constitute a privacy breach if they inform another relative.
5. Can loan recovery agents call my relatives at night?
While lenders should follow RBI guidelines they will still make calls at all hours. RBI instructs lenders not to contact borrowers before 8: 00 a.m. and after 7:00 p.m. for late payments. Record calls if you receive them outside of these times.
6. Can I file a complaint against an NBFC recovery agent?
Yes. Submit a written complaint to the NBFC following their compliance grievance department. A physical submission will provide you with a paper trail. Keep a copy of your complaint, any acknowledgment they provide and supporting evidence.
7. What should I do if my relative cosigned my loan?
A co-signer/guarantor has different rights than your other family members. The responsibilities of Guarantors & Co-applicants are the same as the borrower. You may want to discuss the situation with that relative before escalating.
8. Can I settle my loan out because agents are calling my family?
Settlement may be possible but is subject to the lenders terms. You are not entitled to early settlement this is up to the lender. Get all settlement agreements in writing. Confirm with the lender before wiring any money.
9. Can Loan Settlement Lawyer help me if agents harass my family?
Loan Settlement Lawyer will review loan paperwork, calls/recovery emails and help you understand how best to respond. Contact us to speak to an attorney about your situation.
10. When should I consult a lawyer about loan recovery calls?
Once you or your relative are harassed, or confidential information has been shared with family members it might be time to speak with a lawyer. You can always contact a lawyer first to review your loan documents.
Final Thoughts
Borrowers who has defaulted on a loan has responsibility to repay the legitimate amount but that doesn’t give them right to harass and embarrass the borrower and his family members.
If your family members are getting harassed by recovery calls (If they never co-signed or gave guarantee to the loan legally) do not argue with each and every caller. Keep a log of calls and get advice regarding the proper complaint/legal course of action.
Loan Settlement Lawyer can assist borrowers across Delhi NCR and India regarding recovery calls, analyzing loan documents, settlement negotiations and any legal matter. Please meet Advocate BK Singh to review your account and you can decide whether to settle the account, restructure the loan, escalate a complaint or pursue some other legal avenue.