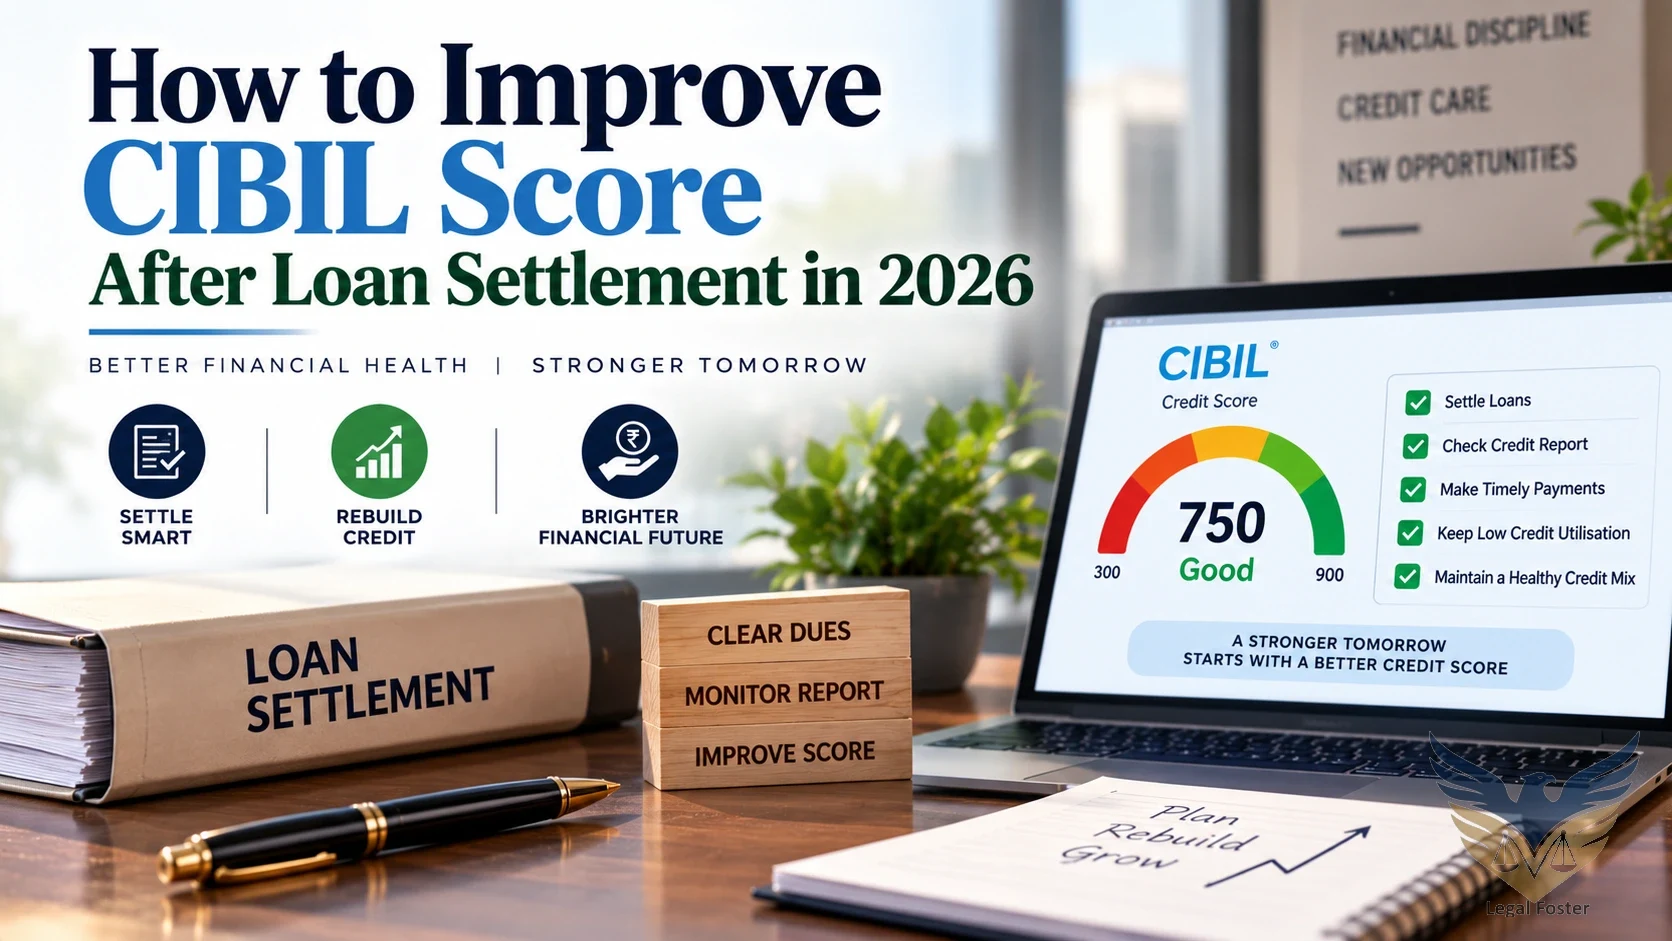
How Can You Improve Your CIBIL Score After Loan Settlement in 2026?
Loan settlement will help you resolve your financial hardship but at what cost? A poor CIBIL score.
You paid up the negotiated settlement amount, got the bank’s No Objection Certificate and are happily receiving no more calls from recovery agents. However, when you apply for a new loan or credit card your application may well get rejected by the lender.
What gives?
When you negotiate a settlement that allows the bank to mark your loan as “Settled” instead of “Closed”, it is because the lender has agreed to accept less than the outstanding amount as a full and final payment. Any lender you approach in the future will see that entry on your credit report and may think twice about lending to you.
If you’re wondering how to improve CIBIL score after loan settlement, you’re not alone. It requires cleaning up incorrect credit information, continuing to make payments on time and slowly re-establishing positive credit history. You can also explore CIBIL dispute guidance and credit report correction help if you believe your lender has reported inaccurate information.
A person in Noida settled a personal loan after losing his job. After paying the settlement amount and six months of on-time EMIs for a new vehicle loan, he learns that the settled loan is affecting his loan eligibility. Simply settling his earlier loan didn’t delete his repayment history.
Small business owners in Delhi, households in Ghaziabad and borrowers in other cities who have settled credit cards, business loans or unpaid personal loans have faced similar challenges.
Loan Settlement Agency’s Advocate BK Singh can help you if your settlement agreement, misreporting or disputes with your lender need to be reviewed from a legal perspective.
Recovering your credit score will take time, but there are steps you can take to make a difference. Learn what information banks are reporting to credit bureaus, what errors you can dispute and how your future payments factor into your credit score. You’ll be able to make informed decisions and avoid costly mistakes.
We cover the legalities in India in 2026, steps you can take to start repairing your credit and when you may want to consider professional help.
Why Does Your CIBIL Score Matter After Loan Settlement in India in 2026?
Lenders use your CIBIL score to evaluate your personal loan, home loan, vehicle finance and credit card applications. Depending on the lender’s underwriting guidelines and your overall credit history, a settlement may cause your application to be scrutinised further, increase your interest rates or even get rejected.
If your score is low, not all lenders may decline your loan application. Lenders such as banks also evaluate your salary, current liabilities, job security and EMI servicing ability before approving a loan.
Many people across Delhi NCR, Mumbai, Pune, Bengaluru, Hyderabad, Chennai and other cities in India apply for credit to meet their housing loans, education loans, or business finance requirements.
If you are working towards rebuilding your credit score, an unsettled settlement entry can become a major hurdle in your journey.
Settlement notices explained: BK Singh can help you analyse your settlement letter and determine if you have a dispute with the bank over a reporting error, missing documents or an authentic past entry.
For a broader overview of the process, see our loan settlement consultation services.
Quick Facts About CIBIL Score Recovery After Settlement
- A loan reported as “Settled” typically indicates the lender agreed to receive less than the full amount due.
- A settlement does not erase your previous CIBIL score.
- Negative repayment history, if accurate, cannot usually be deleted at the borrower’s request.
- Credit information companies will typically retain repayment history in accordance with applicable reporting and retention standards.
- If there are inaccuracies, you can ask to have them corrected.
- Make regular repayments, use credit responsibly and maintain lower outstanding balances to help improve your rating over time.
- RBI’s Credit Information Framework lays down guidelines for reporting, corrections & grievance redressal.
What Happens to Your CIBIL Score After Loan Settlement?
Loan settlement means when the lender agrees to receive some agreed upon amount to an outstanding loan. If you agreed to pay less than what's due on your account, it may be listed as settled instead of paid as agreed.
Your CIBIL score is a three-digit credit score based on your credit report details like repayment history, credit mix, credit utilisation, enquiries etc.
Settlement will impact your credit profile as it shows that you didn't pay your original debt as agreed.
For borrowers dealing with unsecured debt, the personal loan settlement guidance service explains settlement terms, payment documentation, no-dues follow-up and CIBIL-related concerns.
What Indian Laws Govern Credit Reporting and Loan Settlement?
The laws that govern India’s credit reporting ecosystem are the Credit Information Companies (Regulation) Act, 2005 (CICRA), the rules framed under it, any regulation made under CICRA, and directions issued by RBI.
Credit institutions report information to the credit information companies that are registered with RBI (CRIF High Mark).
Borrowers Right to Correct Credit Information
Creditors have the right to request that incomplete, incorrect or misleading information be corrected.
If a bank receives payment in full as per a settlement agreement, but continues to report an outstanding balance, you can file a dispute.
Typically it’s required to have confirmation from the lender first because the credit bureau has only what the lender reports to them.
You can’t demand that an accurate report of a settlement be changed to show a regular account closure to boost your credit score.
RBI Complaint and Compensation Guidelines
Reserve Bank of India’s framework to address credit information related grievances allows borrowers to make such requests for correction and file complaints.
As per the compensation framework, eligible complaints for delayed updating of credit information i.e. beyond the specified timeline of 30-calendar-days could be eligible for compensation at the rate of ₹100 for each day of delay, subject to terms and conditions and fault.
So if your dispute fails you are not entitled to compensation.
An eligible complaint which is not resolved can be further pursued through the lender’s grievance redressal process and, if applicable, the RBI Integrated Ombudsman Scheme, 20 21.
Advocate BK Singh can help you if the lender refuses to look at your proof or a dispute with the credit bureau remains unresolved. Where appropriate, you can also review the available borrower assistance services for CIBIL guidance, complaint support and settlement-related documentation.
Who Should Take Steps to Rebuild Their Credit Score?
Credit rebuilding advice applies to customers who paid off personal loans, credit cards, business loans or any other credit product during times of financial distress. Professionals seeking to buy a home may want to check their credit history months before applying for a home loan. Even small business owners can encounter the same issues when applying for a working capital loan. Students and families who have had past due payments or who had to pay off loans during medical or job emergencies can also gain from reading this article.
Across India, borrowers can now access their credit score online for the first time without having to visit a bank branch. This is especially helpful for consumers living in Delhi, Gurugram, Greater Noida, Faridabad, Meerut, Jaipur, Lucknow and other major cities. While the financial measures mentioned in this guide apply to most citizens, there can be variations in bank policies and personal situations.
Borrowers facing housing finance difficulties can also review the home loan settlement guidance service for information about overdue EMIs, settlement documentation, lender communication and CIBIL concerns.
Which Documents Should You Keep After Settling a Loan?
Maintain all documentation relating to the settlement deal, even after the lender has left you alone.
This includes:
- Loan documents and associated account statements.
- The settlement offer and your acceptance in writing.
- Evidence of all settlement payments.
- Settlement confirmation or no dues letter if provided.
- Correspondence including emails, letters and messages with the lender.
- Credit reports before and after settlement.
- Credit bureau dispute verifications and lender replies.
- Documentation related to any outstanding dispute regarding dues.
Note that a payment receipt may not necessarily confirm all the terms of your settlement. Correspondence (written) that explains the lenders acceptance of your payment as per your agreed amount can be very useful. Advocate BK Singh will review these documents when a borrower approaches him for help determining what the lender agreed to and if the reporting was done accordingly.
How Long Does It Take to Improve CIBIL Score After Settlement?
Settling does not have a set timeline for CIBIL score recovery. Reports are refreshed when lenders report periodically. How it improves depends on what is on the current report, your current credit activity and the model used to score you. Once settled an account can show for years under the applicable credit bureau retention guidelines.
There is no general right to have a correct settlement entry deleted after a few months. Borrowers should separate three issues: fixing a reporting mistake, updating a fully settled account and improving their score.
Correcting a mistake may have a defined complaint process. True score recovery can take an indeterminate amount of time. If an incorrect entry persists you may contact Advocate BK Singh after you've tried writing to the lender and credit company.
For more information on the wider reporting process and how a settlement may affect future applications, read How Does Loan Settlement Affect CIBIL Score and Credit Report?
When Should You Consult a Lawyer About a CIBIL Dispute?
Legal intervention is advised when the issue is related to promises to pay, wrongful credit reporting or unresolved lender issues.
This could include situations where the bank is persistently asking for money that seems unfair based on an agreed upon full- and- final settlement or when the lender will not consider proof of an inaccurate entry on a credit report.
Issues with guarantor liabilities being contested, mismatched settlement letters and receiverv ongoing collection calls could also be reviewed.
Legal assistance is not needed to make a simple plan to improve your credit.
BK Singh can help you determine if the information you have suggests there is a legal claim to be made or if the borrower simply needs time and new payment behavior.
If a lender has sent a formal demand or notice relating to a disputed account, you can explore the legal notice reply service to understand how your documents and position may be recorded in a written response.
How Can Loan Settlement Agency Help Borrowers?
Loan Settlement Agency is a single point contact for borrowers having loan settlement issues, communicating with lenders and managing documentation etc.
If your settlement was done but you are facing issues such as disputed reporting or unsubstantiated demands, start by reviewing the paperwork/settlement agreement and confirming lender records.
BK Singh can advise you on having the settlement agreement, correspondence and potential remedies reviewed by an attorney.
Disclaimer: Assistance may be provided to borrowers in Delhi NCR, Ghaziabad, Noida, Mumbai, Bengaluru, Hyderabad, Kolkata, Ahmedabad and other cities in India depending on the issue and resource availability.
A reputable attorney will not guarantee an immediate increase in your CIBIL score or a guaranteed deletion of legitimate settlement information.
Frequently Asked Questions
1. Is it possible to increase my CIBIL score after settling my loan?
Yes. You can slowly improve your score by paying your EMIs on time and decreasing your credit card balances while following sound credit practices. It will take some time for your credit score to improve, but how long it will take is determined by your credit history.
2. How quickly can my CIBIL score recover after settlement?
There’s no surefire answer to this. It might take months or even years, depending on how you pay your debts and other loans. You might be able to boost your credit score if you’ve got a decent history of on-time repayments and a low level of debt.
3. Can I erase settled status from my CIBIL report?
You normally can’t erase accurate settled history from your credit report because you asked for it to go away. Reach out to both the credit bureau and bank if your lender has reported something incorrectly.
4. Will my CIBIL score go up after settling a loan?
Settling an outstanding loan will not automatically raise your credit score. Your creditworthiness will continue to suffer from late payments you made before the loan was settled as well as the fact that your loan was settled.
5. Can I apply for a personal loan after loan settlement?
You may qualify for a loan after settling one based on your salary, current debt, and payment history. Whether or not you’ll be able to receive a personal loan is entirely up to the lender and whether or not you meet their lending requirements.
6. Will I get my CIBIL score improved by getting a no-dues certificate?
A no-dues certificate from your lender simply states that the lender has no outstanding dues against your name. It will assist you in proving that your loan was settled, but it will not enhance your credit score.
7. Can I increase my CIBIL score without availing a new loan?
Yes, your score can recover if you make your debt payments on time every month, keep your credit utilisation low, and verify that the information on your credit report is correct. You do not need to take another loan.
8. What should I do if my bank wrongly reports loan settlement?
Send a written request to the bank outlining your issues. Then you may dispute something on your credit report with the credit bureau. Save a letter from the lender about your loan being paid, as well as receipts from your payments and account statements.
9. Will loan settlement affect my home loan eligibility in future?
Yes. It might alter how lenders view your ability to pay loans in the future. Furthermore, your home loan eligibility will be influenced by your salary, debt, credit history, and the lender’s underwriting standards.
10. Can a lawyer help me with CIBIL score after settling my loan?
Yes. Advocate BK Singh can assist you in double-checking your loan settlement documents, your CIBIL score, as well as any inaccuracies that the lender may have reported to the CIBIL. Advocate BK Singh can assist you with disputes with the lender that you haven’t yet resolved. Lawyers cannot force these items to be deleted from your record or increase your CIBIL score to exactly where you want it to be.
Final Thoughts
Loan settlement and CIBIL score repair are two different things. Accept that fact and then .Read your credit report, keep all your settlement documentation, dispute the legitimate errors and continue to pay all your loans on time. Avoid falling prey to promises of overnight miracles. A legitimate negative entry can continue to impact your loan prospects even after the settlement is fulfilled. If the issue is due to misreporting, mismatch in settlement terms or pending demands by the lender, you can always consult Advocate BK Singh at Loan Settlement Agency and we will analyze the legal and documentary factors.